How a DSCR Loan Works for an Airbnb Property
Investors often hit a wall when a traditional mortgage won’t count Airbnb cash flow. A DSCR loan focuses on the rental property’s income rather than relying on W‑2 income. Below, I explain what the ratio measures, how lenders may assess the numbers, and where potential pitfalls can arise.
What a DSCR Loan Measures for an Airbnb Property
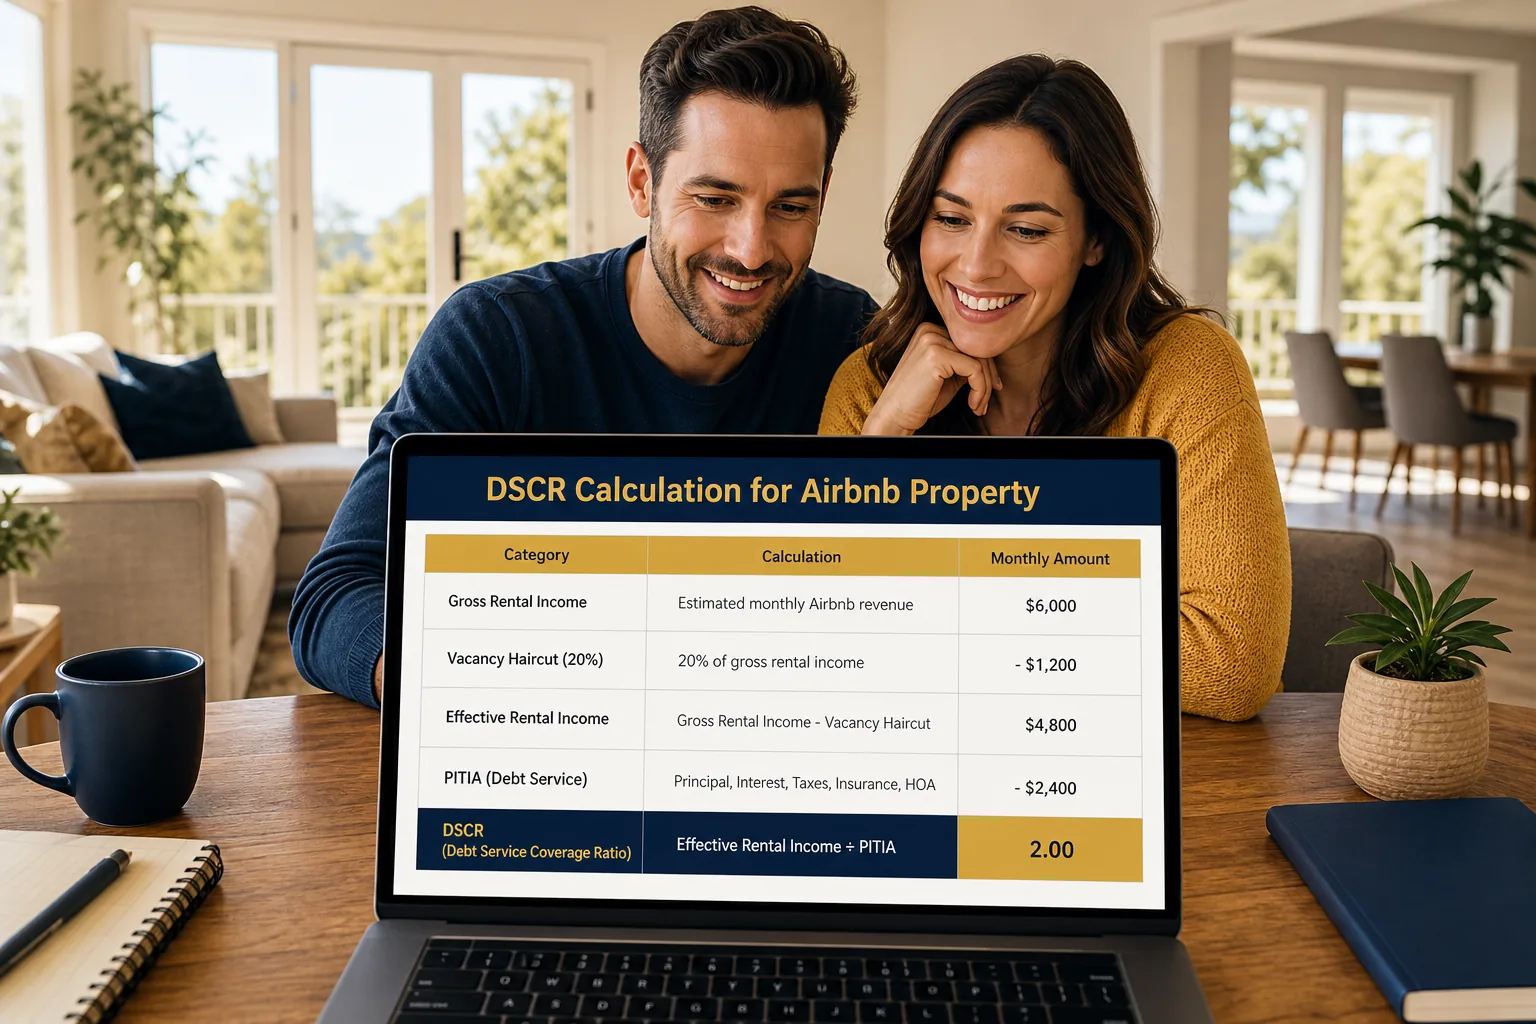
A DSCR loan looks at the property’s ability to cover its monthly debt payment. Lenders divide qualifying monthly rent by the total monthly PITIA: principal, interest, taxes, insurance, and HOA fees. If the result is 1.0, the qualifying rental income equals the payment; a figure above 1.0 indicates a cushion.
Because the calculation starts with rental income, lenders may adjust it for vacancy, cleaning, and platform fees. The remaining figure is the qualifying income they compare with the mortgage payment. Requirements vary by lender.
Key Takeaway: A higher DSCR indicates that qualifying income exceeds the monthly loan cost used in the calculation by a larger margin.
How Lenders Evaluate Airbnb Rental Income
Most lenders start with the loan type. Conventional mortgages may allow a portion of documented Airbnb income to count, subject to program requirements and tax documentation. DSCR loans generally focus on the property’s cash flow rather than the borrower’s personal income.
Projected short-term rental income may be adjusted, and a long-term rent estimate may produce a different qualifying figure.
For conventional financing, lenders may use only a portion of rental income to account for operating costs and vacancies, and tax-return documentation may be required. DSCR programs have their own rules for rental income and reserves. The lender’s chosen income method and underwriting requirements affect the final DSCR, so ask how the calculation will be made for your property.
Pro Tip: Ask the lender which income source they’ll use before you spend time gathering documents.
Property Costs, Seasonality, and Other Factors in the Calculation
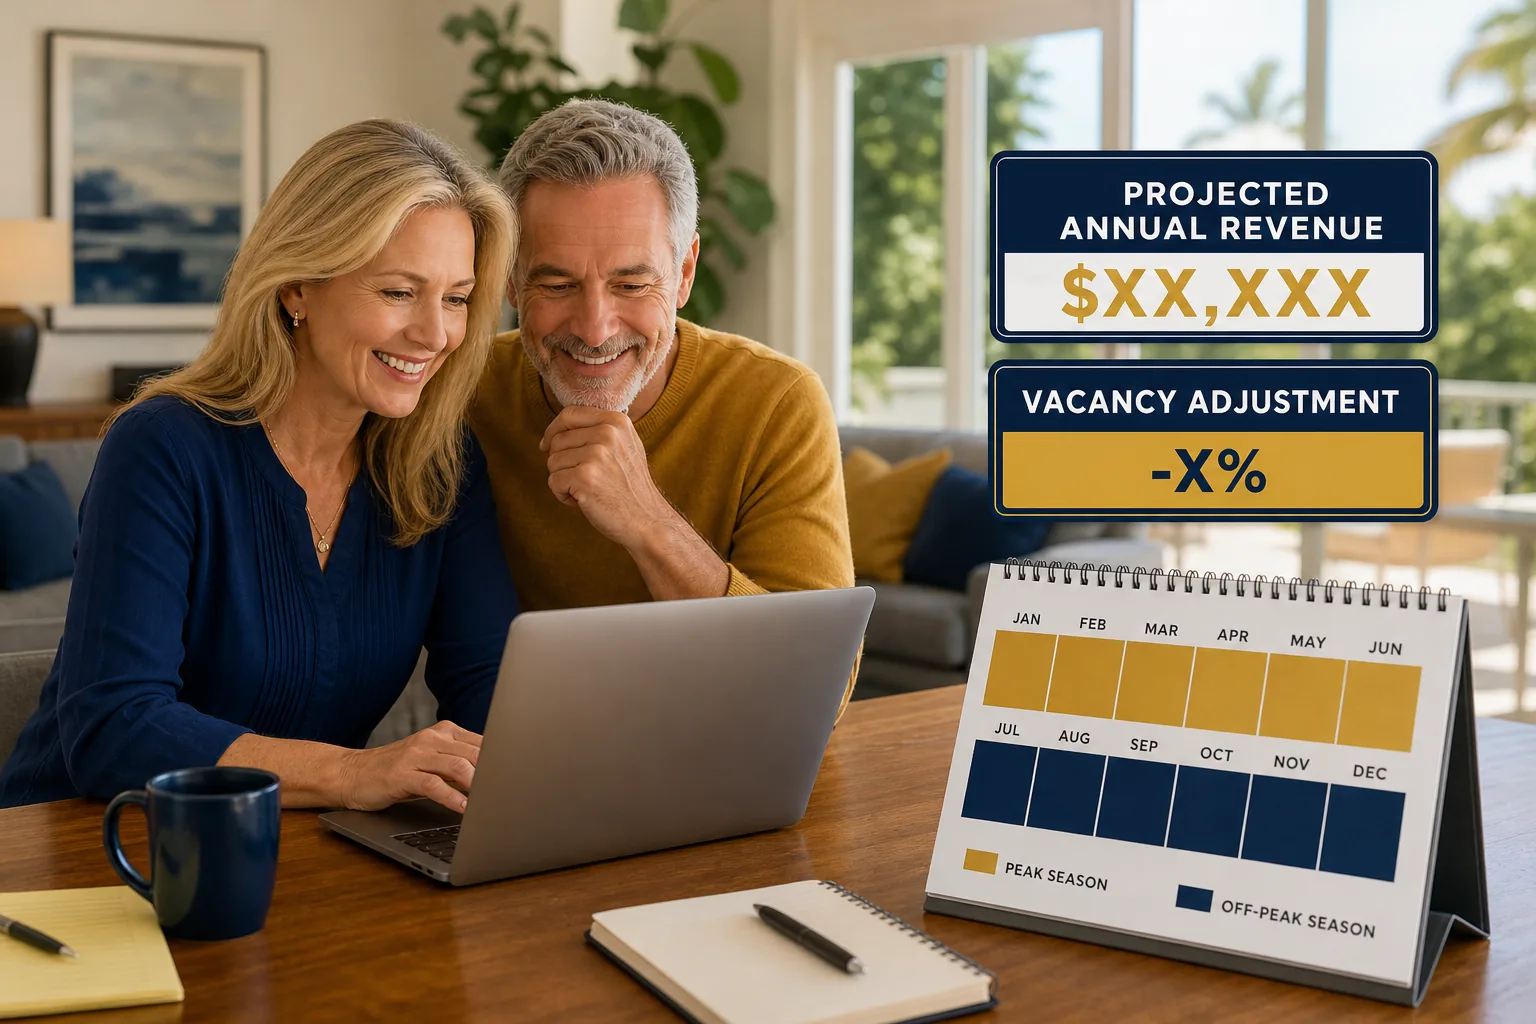
Beyond rent, lenders include recurring property costs in the PITIA denominator. Taxes, insurance, and HOA dues are common components; some programs also have reserve requirements. Seasonal markets add another consideration: a beach condo may earn substantially more during peak season than in winter. To account for variation, a lender may annualize projected income and apply an adjustment.
If comparable short-term rental data is limited, a lender may use a different income-assessment method. That can affect qualifying income, depending on the property and the lender’s method.
Another factor is the loan-to-value (LTV) limit. A higher LTV can increase borrowing relative to the property value, but it can also raise the monthly payment and affect the DSCR calculation. LTV limits vary by program, property, and borrower qualifications.
Key Takeaway: In a highly seasonal market, a vacancy adjustment can be the difference between a DSCR that meets a lender’s criteria and one that does not.
Borrower, Property, and Short‑Term Rental Eligibility
Lenders may also review the borrower’s credit history, cash reserves, and ownership structure. Minimum credit requirements and reserve amounts vary by program; the lender can explain how those factors affect the file.
The property itself must be legally permitted for short-term rentals. Zoning codes, HOA rules, and local restrictions can affect eligibility even when the projected income appears sufficient.
At ABS Home Mortgage, I help investors understand the documentation involved for properties in Illinois, Florida, Georgia, and Texas. Our team can help you identify zoning questions to verify, gather required AirDNA or management-company reports, and review reserve requirements. Those requirements depend on the lender and program.
Some lenders may also require the loan to be held in an LLC or trust. That structure does not necessarily remove personal guarantees, and its legal and tax implications depend on your situation. Consider consulting an attorney or CPA about the appropriate ownership structure.
Pro Tip: Keep reserve accounts separate from your operating account so the lender can more easily verify available funds.
When DSCR Financing May Fit—and What to Ask a Lender
DSCR loans may be worth exploring when a property has rental income but the borrower’s personal income documentation does not fit a conventional mortgage process, such as for some self-employed investors or foreign nationals. They may also be an option for a cash-out refinance when an existing property generates rental income. Eligibility and terms depend on the lender and borrower.
Before you proceed, ask these questions:
- What income source will you use: AirDNA, actual payouts, or appraisal rent?
- What minimum DSCR, if any, does the program require?
- What LTV limits apply to short-term rentals in my state?
- Does the program include a prepayment penalty?
- How many months of PITIA reserves must I have available?
At ABS Home Mortgage, I can discuss DSCR options and how a lender may assess the rental cash flow for an eligible property. Program features and availability vary by location and borrower qualifications. Explore DSCR loan options at ABS Home Mortgage to learn more and consider how the numbers may work for your target market.
Key Takeaway: A DSCR loan focuses on property income, but documentation, underwriting, and processing timelines vary by lender and file.
Considering financing for an Airbnb with a DSCR loan? Read our rental‑income‑based financing guide and contact us to discuss your options.
Conclusion
If you have Airbnb rental income and want to explore financing that focuses on property cash flow, a DSCR loan may be an option to consider. Contact ABS Home Mortgage to discuss your property and review the loan structures that may be available.
Common questions
What is a DSCR loan?
A DSCR loan is a mortgage that primarily evaluates a property’s rental income rather than the borrower’s personal earnings. The lender calculates the debt-service-coverage ratio and uses it as a key qualification measure.
How is the DSCR calculated for an Airbnb?
The ratio equals qualifying monthly rent, after any lender adjustments, divided by the monthly PITIA payment. For example, qualifying rent that is 1.25 times the PITIA results in a DSCR of 1.25.
Do I need a certain credit score for a DSCR loan?
Credit requirements vary by lender and program. A lender may also consider reserves, the property’s rental history, and other factors when reviewing an application.
Can I use a DSCR loan for a property that hasn’t been rented yet?
Some lenders may accept a third-party market analysis like AirDNA for a property without a rental history. The lender decides whether the projection is acceptable and how to adjust it when calculating qualifying income.
What reserves do I need?
Lenders may require liquid reserves, with the amount depending on the program, DSCR, borrower qualifications, and whether the property has a proven rental history or projected income.
Are DSCR loans available in every state?
ABS Home Mortgage offers DSCR loans in Illinois, Florida, Georgia, Texas, and many additional states, subject to program availability and property location. Availability varies, so ask about the state where the property is located.
Follow us on Google: Add ABS Home Mortgage as a preferred source
More in DSCR & Investor · All mortgage guides