How to Get Preapproved for a Mortgage: A Step-by-Step Guide
You’re scrolling listings and wonder if you can actually make an offer. The answer starts with a mortgage pre-approval. Below are the five steps, in order.
Step 1: Review Your Finances and Credit
First, pull your credit report and look for any surprises. A pre-approval letter hinges on your credit score, debt-to-income ratio, and recent payment history. A pre-approval is generally a lender’s conditional commitment to lend up to a certain amount, based on the information you provide, and its validity period varies by lender. For general background, see consumerfinance.gov. While you’re at it, check the score yourself. You can get a free snapshot from the major bureaus or use a credit-monitoring service.
Next, calculate your monthly debt payments. Add up car loans, student loans, credit-card minimums, and any other recurring obligations. Divide that total by your gross monthly income; the result is your debt-to-income (DTI) ratio. Conventional and non-QM programs may have different DTI requirements.
Take a look at your cash reserves. Lenders look at the savings you have for the down payment and closing costs, and some programs also ask for reserves left over after closing. If you’re a first-time buyer, you may qualify for low-down-payment programs that let you keep more of your savings for closing costs.
Finally, ask yourself whether any recent financial moves could raise a red flag. Large, unexplained deposits, a new credit card balance, or a recent job change can slow the process. If you spot something, address it now, either by providing a source document or by waiting until it settles.
Key Takeaway: A clean credit report, a manageable DTI, and solid cash reserves are the three pillars that keep a pre-approval moving smoothly.
Step 2: Identify the Mortgage Program That Fits Your Situation
Mortgage programs differ in down-payment requirements, credit thresholds, and insurance rules. Conventional and FHA loans have different credit-score and down-payment requirements. VA loans are for eligible service members, veterans, and surviving spouses, and jumbo loans cover homes above the conventional loan limit but often demand a higher credit score and a larger down payment.
At ABS Home Mortgage, we offer conventional, FHA, VA, and jumbo loans in Illinois, Florida, Georgia, and Texas, with DSCR investor loans available in additional states. Our non-QM bank statement programs can use bank statements in place of tax returns, which can help self-employed borrowers whose returns don’t show their full income.
To narrow the field, answer these questions:
- Do you have a stable job history of two years, even if you’ve changed employers?
- Are you buying a primary residence, a second home, or an investment property?
- What’s the maximum down-payment you can comfortably make?
Based on your answers, you can focus on the programs that match your profile. For a quick overview of all the loan types we handle, see our mortgage loan programs page.
A mortgage is a loan secured by the home you buy, repaid with interest over time. Knowing the basics helps you compare the fine print of each program.
Step 3: Gather Documents for Your Mortgage Application
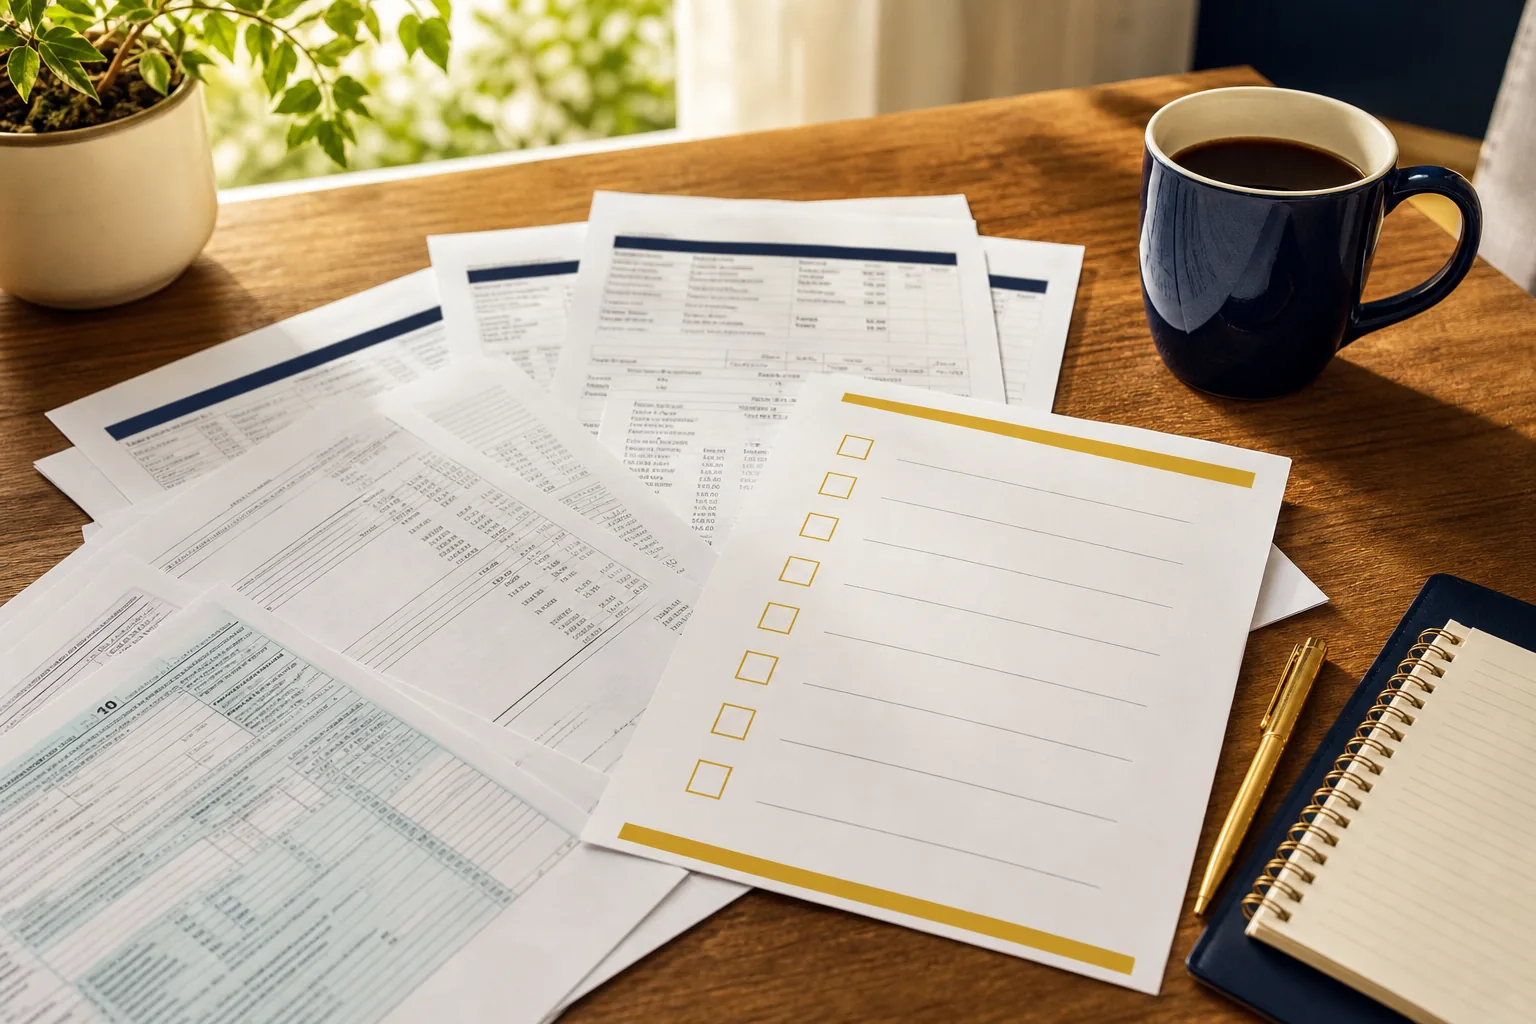
Once you’ve picked a program, start collecting the paperwork lenders will ask for. The most common list includes:
- Two most recent pay stubs (if you’re salaried)
- W-2 forms for the last two years, or tax returns if you’re self-employed
- Bank statements for the past two months for every account you own
- Photo ID and Social Security number
- Proof of down-payment source (bank statement, gift letter, etc.)
Gather the income and bank statements your lender requests. If you own investment accounts, pull those statements as well. They help show you have reserves for closing costs.
For non-QM options, the document list can shrink. Some programs let you qualify on bank-statement income alone, while others accept a profit-and-loss statement instead of tax returns. We’ll tell you exactly which set applies after a quick intake.
Organize everything in a secure cloud folder (Google Drive, etc.) so you can upload files instantly when your loan officer asks. This preparation prevents last-minute scrambles that delay underwriting.
Step 4: Submit Your Application and Compare Available Loan Options
With your documents ready, fill out our online application. The form asks for basic personal info, employment details, and the loan amount you’re targeting. Because we shop multiple wholesale lenders, one application lets us compare options from more than one lender.
After you submit, the lender reviews your application. A pre-approval letter may include a conditional loan amount, an estimated interest rate range, and any conditions you must meet before final approval.
When the offers arrive, compare them side by side. Look beyond the headline rate; consider points, lender fees, and the total cash-to-close. Our how to choose a mortgage lender guide walks you through the exact questions to ask, such as:
- What are the total closing costs?
- Is private mortgage insurance required, and for how long?
- Can I lock the rate, and for what period?
Pro Tip: Multiple mortgage credit pulls within a 30-day window count as one inquiry for scoring, so keep your lender comparisons inside that window.
Step 5: Review Your Preapproval Letter and Keep Your Finances Steady
The pre-approval letter is a snapshot of your financial picture on the day it’s issued. It’s not a final loan approval. The lender will still run a full underwriting check before closing.
Read the letter carefully. It will list any conditions you must satisfy, such as providing updated pay stubs or clearing a credit dispute. If you’re buying an investment property, make sure the letter mentions the DSCR (debt-service-coverage-ratio) calculation we used, because that metric can change if the property’s projected rent shifts.
While you’re house hunting, keep your financial behavior steady. Avoid new credit cards, large purchases, or job changes that could alter your DTI. If you plan to move money between accounts, tell your loan officer first. Large transfers have to be documented, and we can tell you which statements to keep.
If the pre-approval expires before you find a home, you’ll need to send updated documents.
When you’re ready to make an offer, attach the pre-approval letter. It shows the seller that a lender has already reviewed your finances.
Need a quick, no-obligation estimate to see how your numbers look? Get My Rate Quote and we’ll run the numbers for you.
Common questions
What’s the difference between pre-qualification and pre-approval?
Pre-qualification is an informal estimate based on information you give a lender without any documentation. Pre-approval involves a full credit pull and verification of income, assets, and debts, resulting in a conditional commitment.
How many credit inquiries will a pre-approval cause?
A pre-approval usually includes a hard inquiry. If you shop with more than one lender, multiple mortgage credit pulls within a 30-day window count as one inquiry for scoring.
How long does a pre-approval letter stay valid?
It varies by lender. The expiration date is usually listed on the letter itself.
Can I use gifted funds for my down payment?
Often, yes. Many programs allow gift funds with a signed letter stating the money is a gift, not a loan, and the lender may ask for records showing where the money came from.
Do I need a real-estate agent to use a pre-approval?
No, you can apply on your own, but an experienced agent can help you present the pre-approval to sellers and negotiate offers.
What happens if my financial situation changes after I get pre-approved?
The lender will re-verify your information during final underwriting. Significant changes, like a new debt or a job loss, could affect the final loan amount.
Ready to move from pre-approval to closing? Start your application when you’re ready, and we’ll guide you through each step.
Follow us on Google: Add ABS Home Mortgage as a preferred source
More in First-Time Buyer · All mortgage guides