Mortgage Tips & Home Loan Guides | ABS Home Mortgage
Expert guidance on home loans, rates, and the path to homeownership.
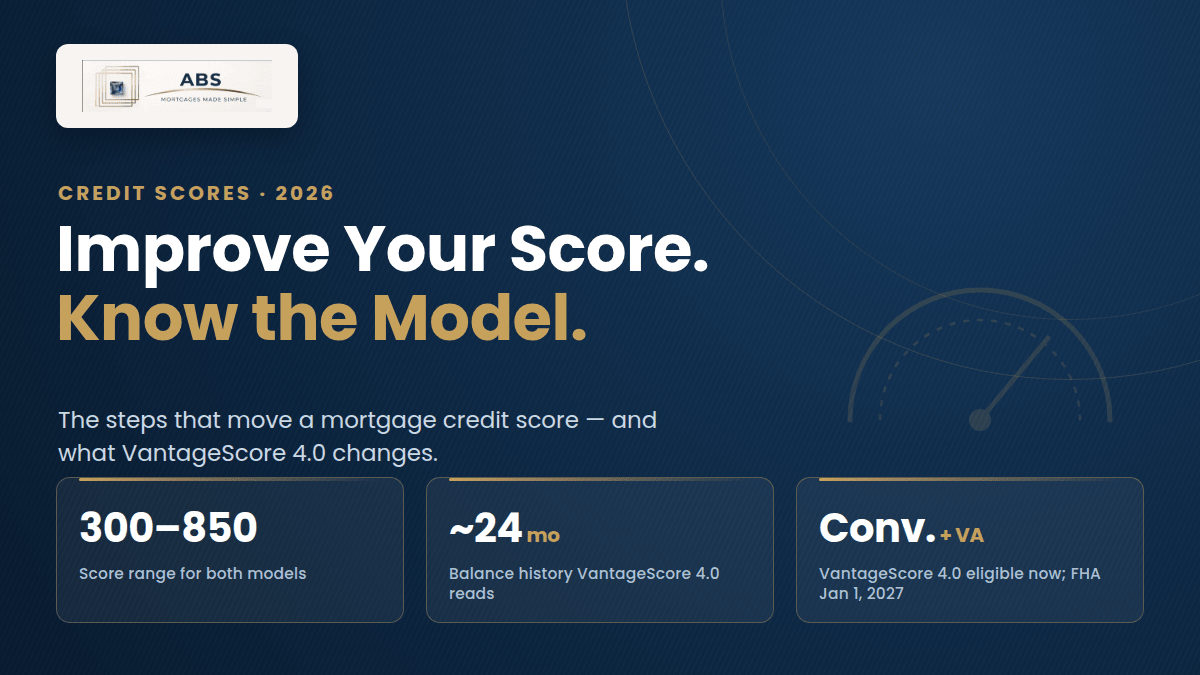
How to Improve Your Credit Score Before a Mortgage, and What VantageScore 4.0 Changes
Fannie Mae and Freddie Mac now let lenders use VantageScore 4.0 as well as Classic FICO. Here's what that does and doesn't change, and the steps that actually move your score before you apply.
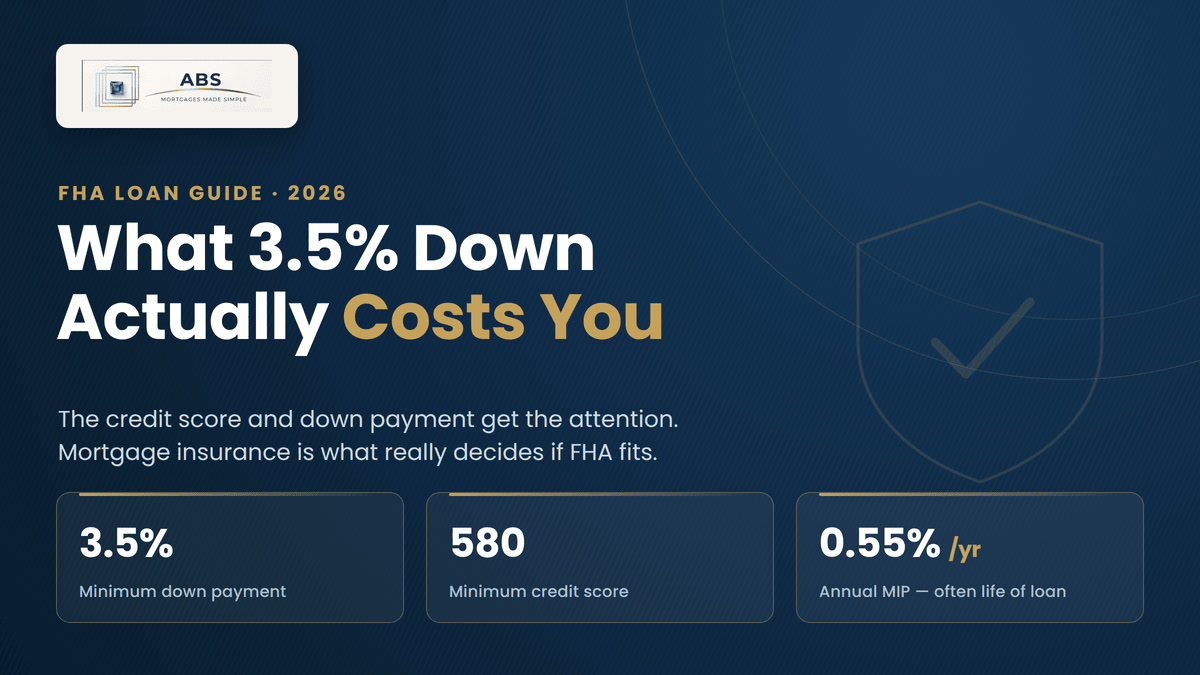
FHA Loans in 2026: What 3.5% Down Actually Costs You
FHA's 3.5% down payment and 580 credit score get all the attention, but the mortgage insurance that often lasts the life of the loan is what actually decides whether FHA is the right fit. Here's how the costs, 2026 loan limits, and requirements actually work.
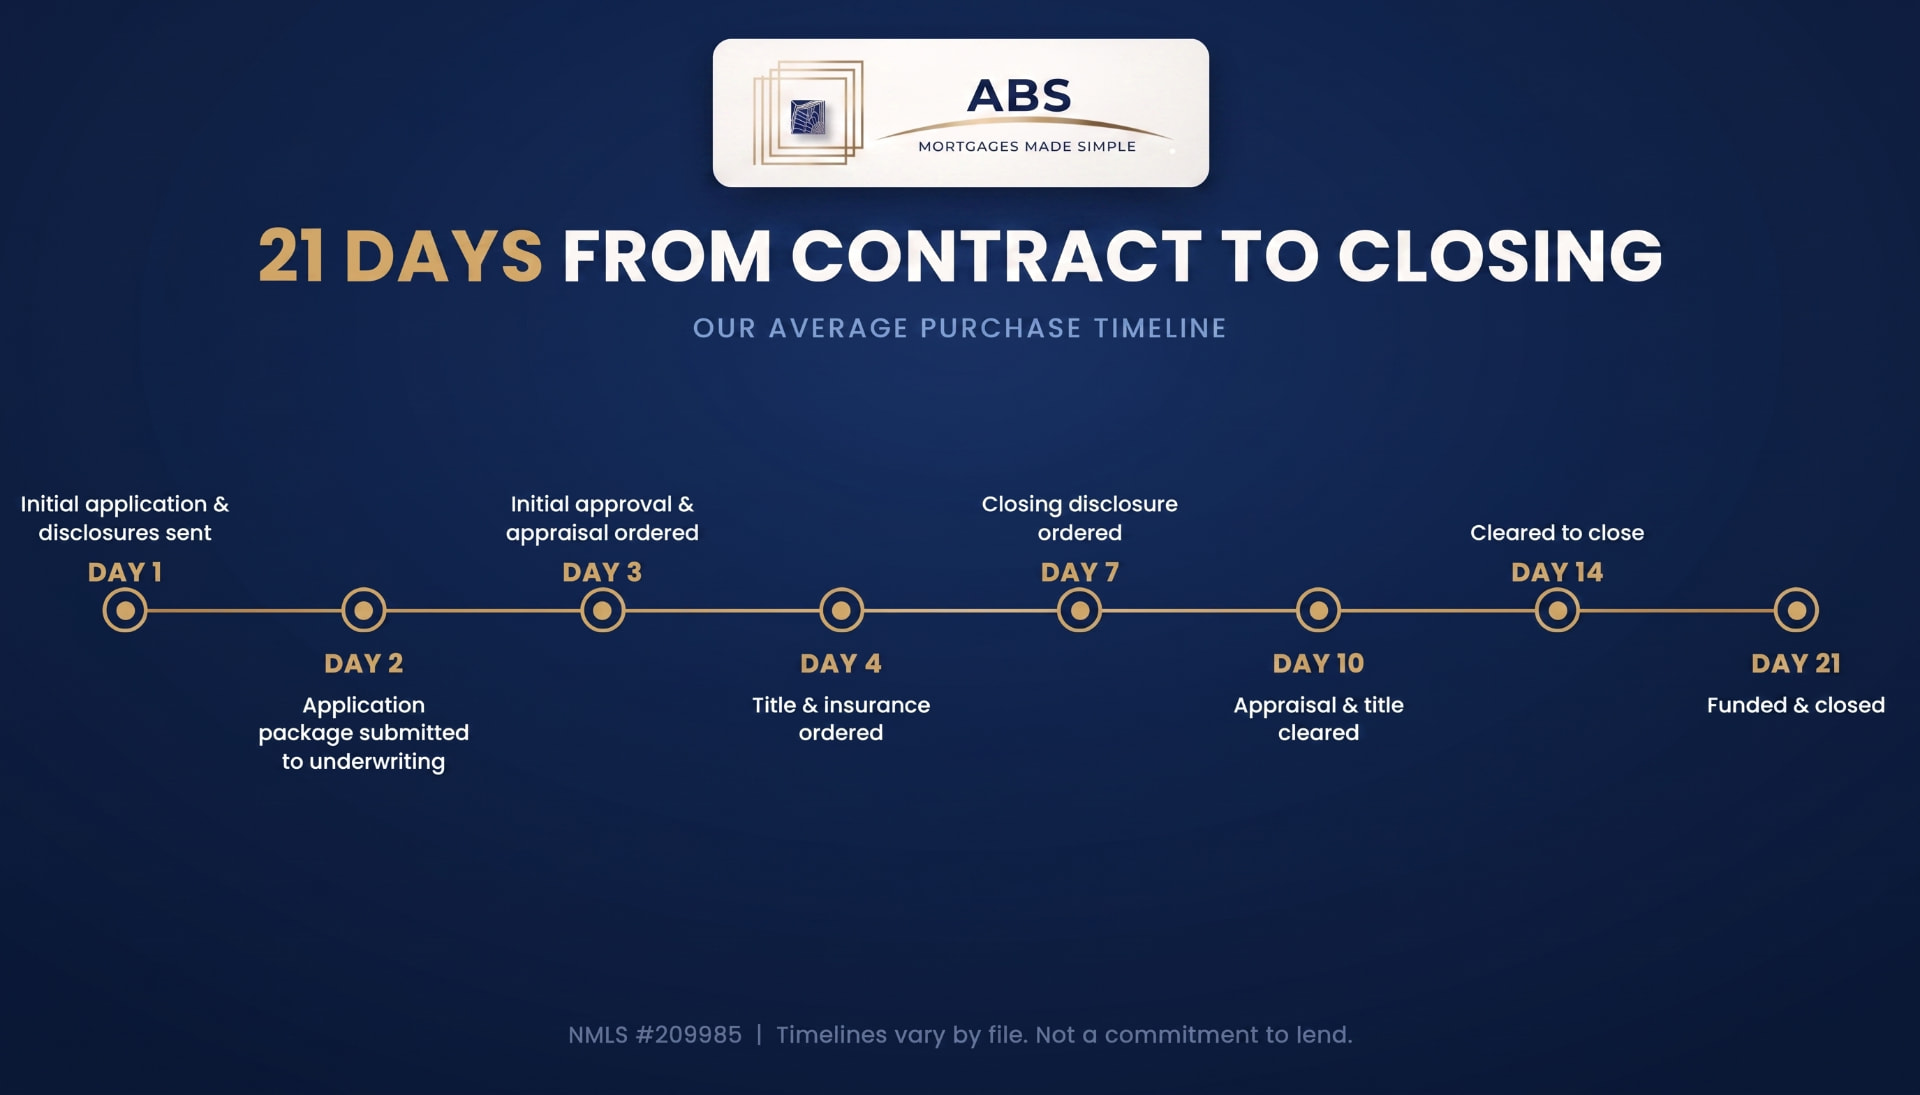
Inside a 21-Day Close: What Happens Each Week, and What Slows It Down
Our average purchase closing is 21 calendar days. Here's exactly what happens each week — document collection, underwriting, appraisal, title, and the Closing Disclosure clock — and the specific points where a normal file actually slows down.
FHA vs. Conventional in Texas 2026: No State Income Tax Doesn't Mean No Trade-Offs
Both loans charge mortgage insurance under 20% down, but in Texas your FHA limit can swing by nearly $275,000 depending on the metro. Plus why "no income tax" doesn't mean a lower payment, TDHCA and TSAHC assistance, and the visa-holder rule change.
FHA vs. Conventional in Florida 2026: Why Your County Decides Both Loan Limits
Both loans charge mortgage insurance under 20% down, but in Florida even the conforming limit moves by county - up to $990,150 in Monroe County. Plus FL Assist, Hometown Heroes, and the visa-holder rule change.
FHA vs. Conventional in Georgia 2026: The Atlanta Metro Line That Changes Your FHA Limit
Both loans charge mortgage insurance under 20% down, but in Georgia the bigger swing factor is your county: FHA reaches $718,750 in 24 metro-Atlanta counties versus $541,287 elsewhere. Plus Georgia Dream assistance and the visa-holder rule change.
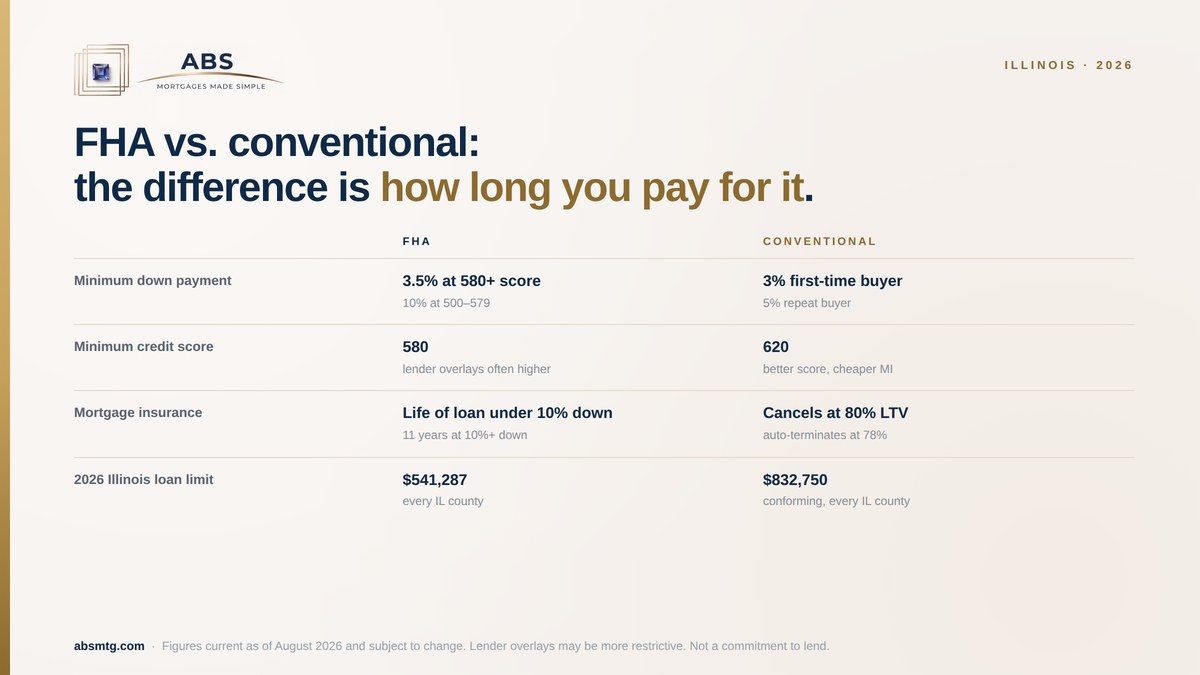
FHA vs. Conventional in Illinois 2026: The Difference Is How Long You Pay for It
Both loans charge mortgage insurance under 20% down. The difference is that conventional PMI cancels and FHA MIP at 3.5% down does not. Plus the 2026 Illinois loan limits, the visa-holder rule change, and how property taxes affect which one you qualify for.

First-Time Home Buyer Guide: Naperville 2026
Everything a first-time buyer needs in Naperville for 2026: what you can actually afford with DuPage County taxes, down payment minimums, neighborhood-by-neighborhood pricing, Illinois assistance programs, and the pre-approval process.