VA Loan Closing Costs Explained: What Buyers Should Expect
Thinking a VA loan means no cash at closing? Not quite. You’ll still face closing costs, and most of them can’t be rolled into the loan.
We analyzed 34 YouTube comments about VA Loan closing costs and found that 21% mentioned high closing cost amounts.
Below we break down the main costs, explain the VA-specific rules, and show how to size your cash-to-close.
What VA Loan Closing Costs Include
Your closing statement lists several kinds of charges. They include:
- Lender-originated fees such as origination, underwriting, and processing.
- Third-party services like appraisal, title search, and recording.
- Prepaid items: homeowners insurance, property-tax reserves, and interest that accrues between closing and the first payment.
You and the seller can negotiate who pays many of these charges, so review each one closely. If you’re still choosing a loan, you can compare our VA, FHA, conventional and jumbo programs.
Bottom line: expect a mix of lender fees, third-party costs, and prepaid items. Your Loan Estimate shows the total for your loan.
VA-Specific Fee Rules and the Funding Fee
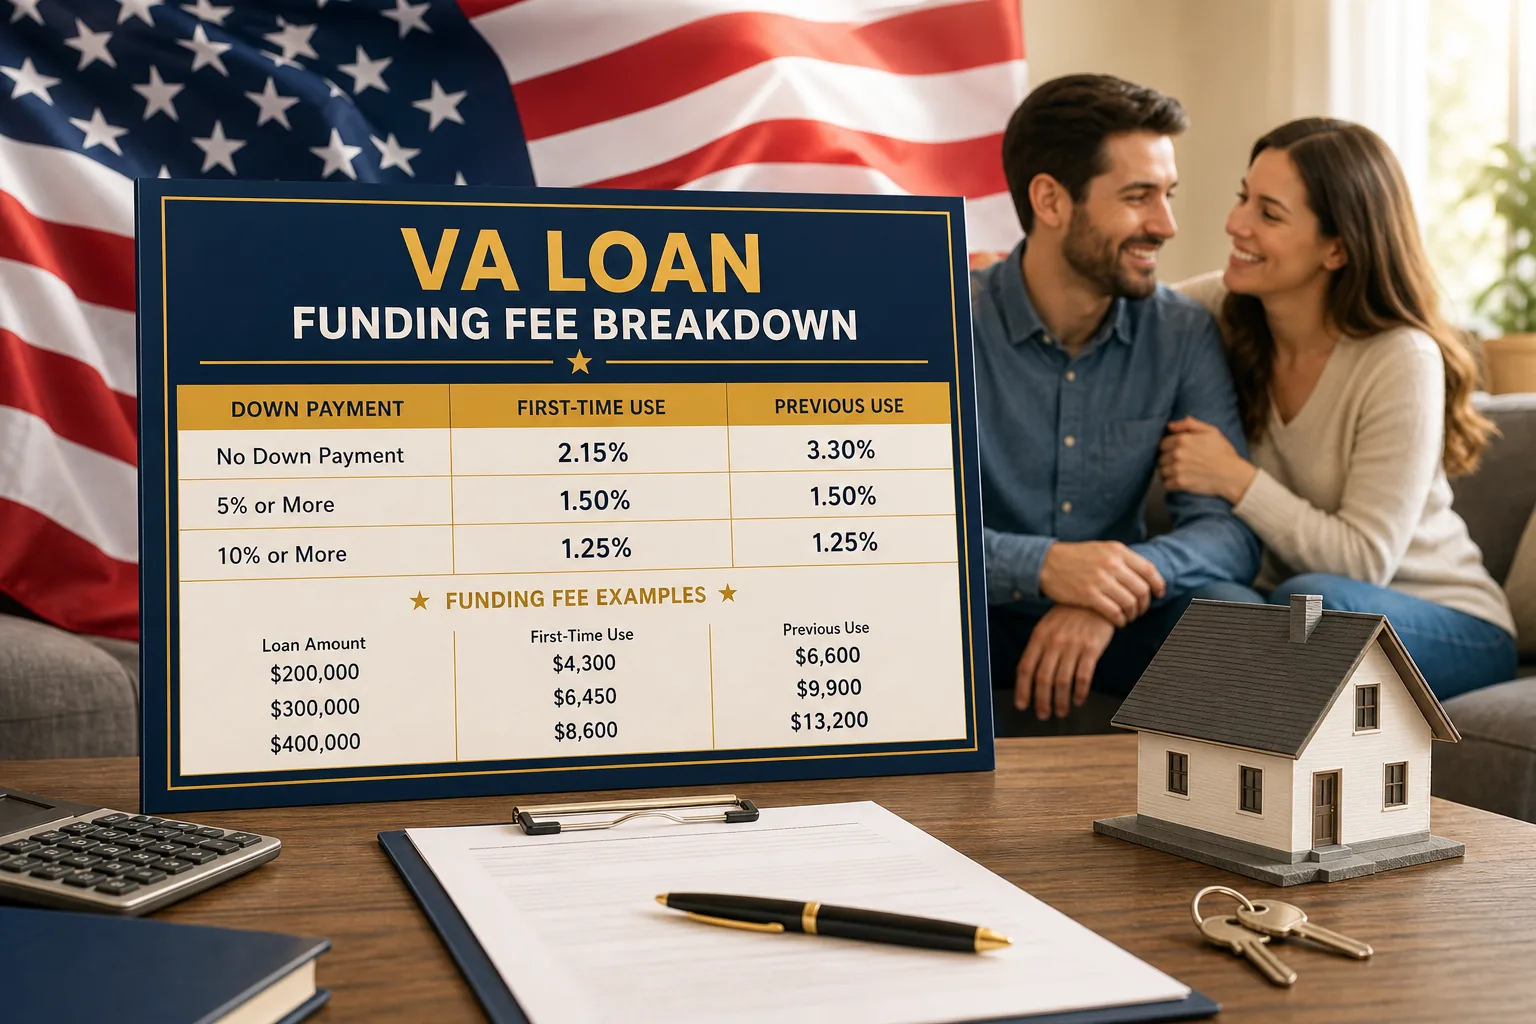
The VA funding fee is a one-time charge on most VA-backed loans. It helps cover the program’s cost to taxpayers, since VA loans don’t require monthly mortgage insurance. VA sets it as a percentage of the loan amount, not the purchase price. On a VA-backed purchase loan, the current chart (effective April 7, 2023) puts the fee between 1.25% and 3.3%, depending on whether you’ve used the benefit before and how much you put down. An interest rate reduction refinance loan (IRRRL) carries 0.5%. Check the VA funding fee chart for your loan type.
You don’t pay the fee if, for example, you receive VA compensation for a service-connected disability, or you receive Dependency and Indemnity Compensation as a surviving spouse. VA lists every exemption on that page. You can pay the fee in full at closing or include it in the loan. Financing it raises your loan balance, and you pay interest on it over time.
On a purchase loan, the funding fee is the only charge VA lets you finance. You pay all other fees and charges when the loan closes.
Pro Tip: Ask whether a lender credit could cover part of your closing costs in exchange for a higher rate. Compare the cash you save at closing with the higher payment over the years you expect to keep the loan.
Common Lender, Third-Party, and Prepaid Charges
Lender fees vary from lender to lender. They can include an origination fee, discount points, and processing or underwriting charges. Your Loan Estimate lists each one.
Third-party costs include the VA appraisal, title insurance, and recording fees. Title insurance usually includes a lender’s policy, and an owner’s policy may be optional. These costs vary by location.
Recording fees and transfer taxes depend on the state and county.
Prepaid items include your first homeowners insurance premium and an escrow reserve for taxes and insurance. Your lender sets the reserve amount.
These charges add up quickly, so check the totals early.
We recommend pulling a detailed Loan Estimate from each lender and comparing line-item fees, not just the interest rate.
Key Takeaway: Lender fees can differ a lot between lenders. Third-party and prepaid costs depend more on the property and its location.
For a deeper look at each cost component, see Understanding Closing Costs on our Learning Center.
Who Can Pay Closing Costs: Buyer, Seller, and Lender
You and the seller can negotiate who pays many closing costs, including the loan origination fee, discount points, the VA appraisal fee, title insurance, and the recording fee. VA doesn’t limit seller credits for normal closing costs. It does limit seller concessions, such as paying your funding fee or paying off a debt, to 4% of the home’s reasonable value. You’ll find that value on the VA Notice of Value.
Lenders sometimes offer a credit in exchange for a higher rate. This “lender credit” reduces out-of-pocket cash but raises the monthly payment.
VA doesn’t require the seller to pay any of these costs, and local customs vary.
You should receive your Closing Disclosure at least three business days before closing. Use it to confirm who is paying what.
If you’re later awarded VA disability compensation with an effective date before your loan closed, you may qualify for a funding fee refund. VA pays refunds issued on or after July 1, 2019 directly to the Veteran.
Understanding these allocation rules helps you negotiate a lower cash-to-close.
For more on how refunds work, see guidance on funding-fee refunds.
How to Estimate Your Cash to Close and Review the Disclosure
Start with the closing costs on your Loan Estimate. Subtract any seller credits or lender credits you’ve negotiated.
Next, decide whether to finance the funding fee. If you roll it in, increase the loan amount by the fee percentage; otherwise, plan for that cash outlay.
The Closing Disclosure breaks down every charge. Compare it line-by-line to the Loan Estimate you received earlier. Review any fee increases with your lender.
Don’t forget prepaid reserves. Your lender may require property-tax and insurance funds in escrow. Ask how much.
Use a spreadsheet or a mortgage calculator to total these items. Our Get My Rate Quote form takes about a minute, and a licensed loan officer sends back a rate, payment estimate, and closing-cost breakdown.
Finally, confirm that the total cash required aligns with your budget, including moving costs and an emergency reserve.
Conclusion
If you’re ready to see a clear cash-to-close number, start a quote with us today and let our experienced team walk you through every fee.
We’re licensed for VA loans in Illinois, Florida, Georgia, and Texas. See how our VA loan program works, or call us at 630-357-1600.
Common questions
What are the typical VA loan closing costs?
They usually include lender fees, third-party charges such as the appraisal and title insurance, prepaid items, and the VA funding fee unless you’re exempt. The total depends on your loan amount, location, and lender, and your Loan Estimate shows it.
Can I roll the VA funding fee into my loan?
Yes, you can finance the fee, but it raises your loan balance and may increase your monthly payment.
Are seller concessions allowed on a VA loan?
Yes. VA limits seller concessions to 4% of the home’s reasonable value. Seller credits for normal closing costs don’t count toward that limit.
Do I have to pay private mortgage insurance (PMI) with a VA loan?
No. VA loans never require PMI, regardless of down payment size.
How can I reduce my cash-to-close?
Negotiate seller concessions, ask for a lender credit, or choose a lender with lower origination fees. Also, consider financing the funding fee if you have limited cash.
What is the deadline to receive the Closing Disclosure?
Lenders must provide the Closing Disclosure at least three business days before your scheduled closing date.
Follow us on Google: Add ABS Home Mortgage as a preferred source
More in Rates & Market News · All mortgage guides