VA Home Loan Credit Score Requirements Explained
Veterans often wonder whether a credit score can affect their ability to use a VA benefit. The short answer: the VA itself sets no minimum score, but lenders may set their own standards. Below, I explain what to expect and practical steps you can consider.
We analyzed 22 YouTube comments about VA home loan credit score requirements and found that 27% mentioned debt-to-income ratio and income considerations.
Does the VA Require a Minimum Credit Score?
The VA program does not impose a minimum credit-score requirement.
In practice, many private lenders have their own credit-score requirements, and 620 is a threshold some use. Requirements vary by lender and can change, so a particular score does not by itself determine whether a loan is available. Some lenders may consider lower scores after reviewing the full application, including income, debts, payment history, and other factors. The VA guaranty does not remove a lender’s responsibility to assess risk, but lender policies differ.
Bottom line: the VA itself does not set a score floor, but you’ll need to find a lender whose requirements fit your circumstances.
Why VA Lenders May Set Different Credit Score Standards
Lenders may add “overlays” to VA program requirements to manage risk. These overlays can include a higher score requirement, tighter debt-to-income (DTI) limits, or requests for additional documentation. Lenders may consider the VA’s residual-income requirements along with their own credit policies, so requirements can vary across institutions.
Lenders that handle a high volume of VA loans may use automated underwriting systems (AUS) to assess applications. Other lenders may review some applications manually. The lender’s process and the details of your application can affect whether a lower score is considered; ask about current requirements rather than relying on a general score range.
The type and size of the loan may also affect a lender’s review. Larger loan amounts can prompt additional review or stricter requirements, depending on the lender’s policies and the borrower’s overall financial picture.
Key Takeaway: Lenders apply different requirements, so ask about their current standards if your score is near or below a threshold they use.
How Credit Score Fits Into the Full VA Loan Review
Credit score is just one part of a VA loan review. The VA requires a calculation of residual income: money left after taxes, the mortgage payment, utilities, and other debts. Residual income helps assess whether a borrower has funds for living expenses.
A lender may consider residual income alongside credit history and other application details. For example, a borrower with a lower score and manageable debts may be assessed differently from a borrower with a higher score and substantial monthly obligations. Each application is evaluated under the lender’s guidelines; neither scenario guarantees an approval or denial.
Lenders may also review payment history, recent delinquencies, and the age of credit accounts. A recent collection that has been paid may be considered in the context of the overall credit profile, but its effect depends on the lender’s review.
Because the VA guarantees a portion of an eligible loan, lender policies may differ from those for some other loan programs. Lenders still assess whether the borrower can manage the proposed payment and meet their underwriting requirements.
What to Do If Your Credit Score Is Below a Lender’s Standard
If your score is below a lender’s stated threshold, you can ask whether it considers applications through manual underwriting. Some lenders may review factors such as a history of on-time rent or mortgage payments, but policies and documentation requirements vary.
You can also review practical steps for improving your credit score before applying. Paying down revolving balances may affect credit utilization, though the impact on your score and the timing vary. Check your credit reports for errors and dispute inaccurate information with the relevant credit bureau. Score changes are not guaranteed, and correcting a report may take time.
Ask the lender whether adding a co-borrower is permitted and how that person’s credit and finances would be considered. A spouse or another eligible veteran may be able to apply with you, subject to program and lender requirements.
It may also help to gather information about factors that could support your application, such as cash reserves, manageable debt, or a documented history of on-time housing payments. The lender will determine how these factors apply to its review.
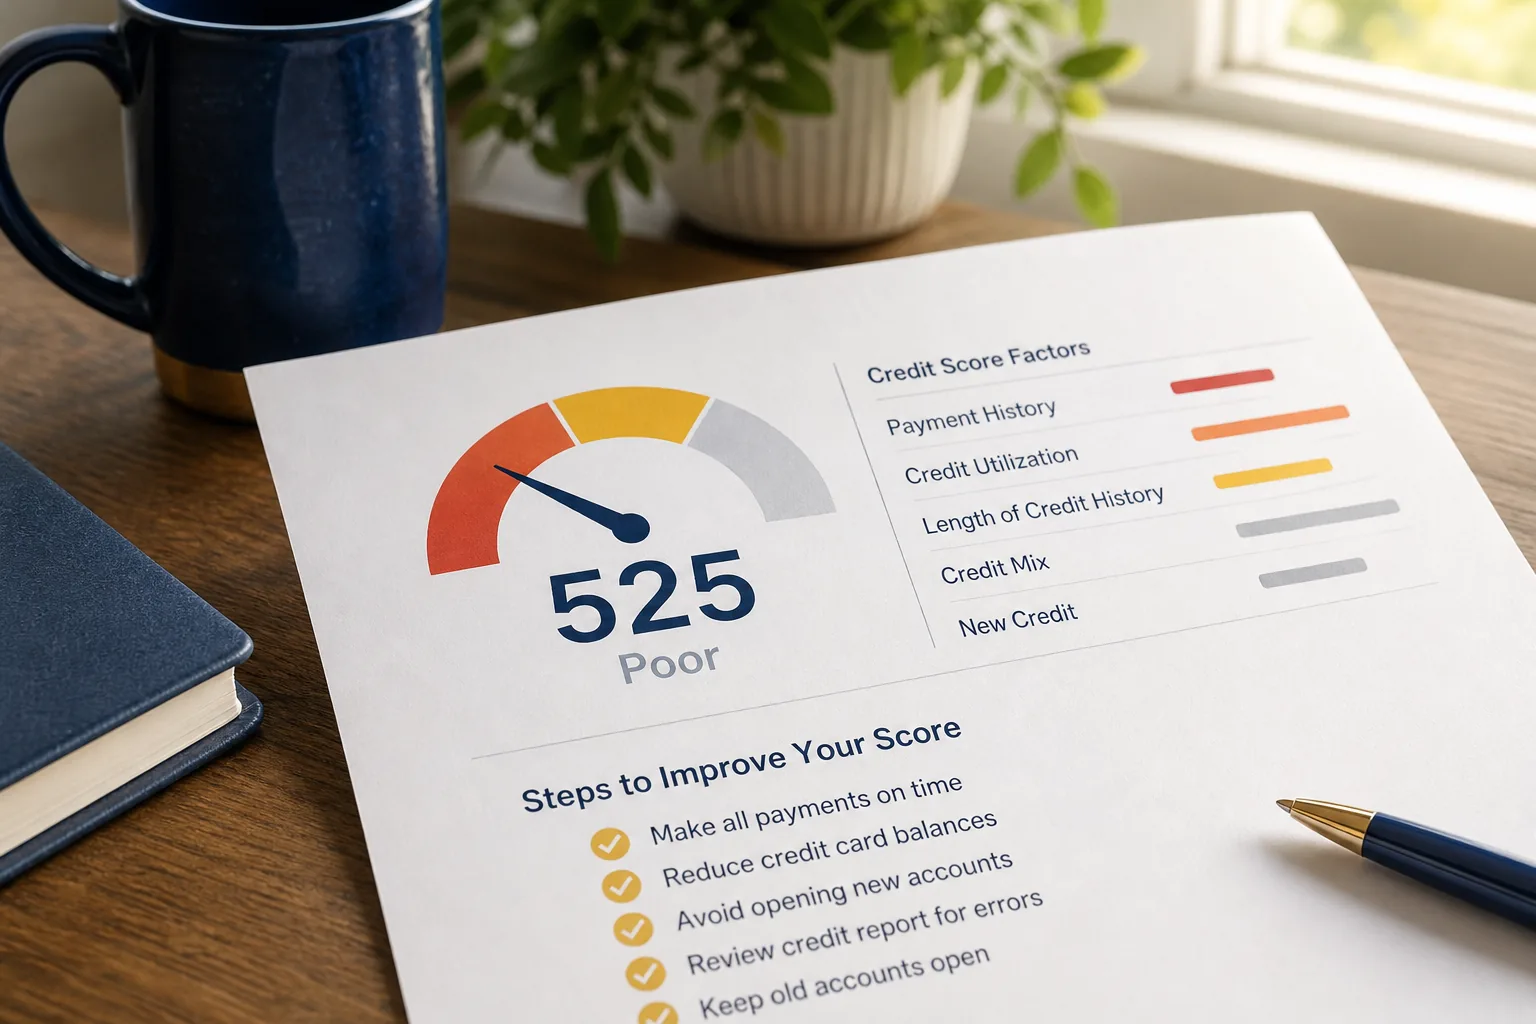
Pro Tip: Request a credit report from an online credit-report provider and dispute any inaccuracies before you apply.
Choosing a VA Lender and Preparing to Apply
At ABS Home Mortgage, we work with a network of lenders and can discuss VA home loan options and lender-specific credit requirements. I’m Bhupesh Saggar, President & CEO (NMLS #221364). ABS Home Mortgage, Inc. (NMLS #209985) is a mortgage broker licensed in Illinois, Florida, Georgia, and Texas. Lender guidelines vary, and a review of your circumstances is needed to understand which options may be available.
When you start the process, ask how a credit inquiry will be handled and whether additional inquiries may be needed. Credit-scoring treatment can depend on timing and scoring models, so don’t assume that every inquiry will have the same effect. We can compare options from multiple wholesale lenders and discuss residual-income calculations and lender-specific overlays.
Before you sign any loan estimate, ask the lender about:
- Minimum credit score and any overlays they apply
- How they calculate residual income for your region
- Funding-fee exemptions you may qualify for
Our team can walk you through the process, from obtaining your Certificate of Eligibility (COE) to closing, while explaining the steps and documents involved.
Key Takeaway: A broker like ABS Home Mortgage can help you compare options from multiple lenders and explain how inquiries may be handled.
If you’re considering a VA loan, you can contact ABS Home Mortgage to discuss your options and decide what steps make sense for you.
For investors who can’t use VA benefits, other financing options may be available for rental properties. Ask lenders about investment-property loan programs and their eligibility requirements.
Conclusion
If you’re considering using your VA benefit, you can discuss your credit profile and possible next steps with ABS Home Mortgage. We can help you compare lender requirements and understand what information may be needed to evaluate your options.
Related reading: VA loan closing costs, how to improve your credit score before a mortgage, how to get preapproved, and whether shopping lenders hurts your credit.
Common questions
Do I need a minimum credit score to get a VA loan?
The VA itself does not set a minimum credit score, but individual lenders may have their own requirements.
Can I get a VA loan with a score below 620?
Possibly. Lender requirements vary, and some may consider applications below a score threshold after reviewing the full financial picture. Ask about current guidelines; eligibility and approval are not guaranteed.
Does a lower credit score affect my interest rate?
A lender may consider credit history when determining loan terms, but the effect varies. Ask the lender to explain the terms available for your application.
What is a VA funding fee and does my credit score change it?
The funding fee is a charge that may apply to a VA-backed loan. The amount can depend on factors such as loan use and down payment, and some borrowers may qualify for an exemption. Credit score does not directly determine the fee.
How many credit pulls can I have without hurting my score?
The effect of multiple mortgage credit inquiries can depend on timing and the scoring model. Ask lenders how they handle inquiries, and review the credit bureau’s guidance for details.
Follow us on Google: Add ABS Home Mortgage as a preferred source
Get your rate quote in about a minute
Answer a few quick questions and a licensed loan officer will follow up with your options.
ABS Home Mortgage, Inc., NMLS ID #209985. Equal Housing Lender. This is not a commitment to lend. Rates, terms, and programs subject to change without notice. All loans subject to credit approval.
Related Reading
VA Loan Closing Costs Explained: What Buyers Should Expect
Learn what VA loan closing costs include, the funding fee rules, who pays what, and how to estimate cash to close.
Read articleHow to Improve Your Credit Score Before a Mortgage, and What VantageScore 4.0 Changes
The steps that actually move your score before you apply, and what VantageScore 4.0 does and doesn't change.
Read articleHow to Get Preapproved for a Mortgage: A Step-by-Step Guide
Learn each step to get preapproved for a mortgage, from checking credit to gathering documents and keeping your finances steady.
Read articleMore in Rates & Market News · All mortgage guides